- $50 an Hour Is How Much a Year After Taxes?
- How Much Is $50 an Hour Annually?
- Understanding Tax Deductions
- Yearly Income After Federal Taxes
- State and Local Taxes
- Social Security and Medicare Deductions
- Net Income Calculation
- Table: Estimated Net Income
- Practical Budgeting Tips
- Common Mistakes and How to Avoid Them
- FAQ: Common Questions About Hourly to Annual Income Conversion
$50 an Hour Is How Much a Year After Taxes?
Calculating your potential annual income when earning $50 an hour can seem straightforward, but don’t forget to take taxes into account. Understanding your net annual income is crucial for budgeting and financial planning. This comprehensive guide breaks down everything you need to know about turning a $50 hourly wage into an annual salary after taxes.
How Much Is $50 an Hour Annually?
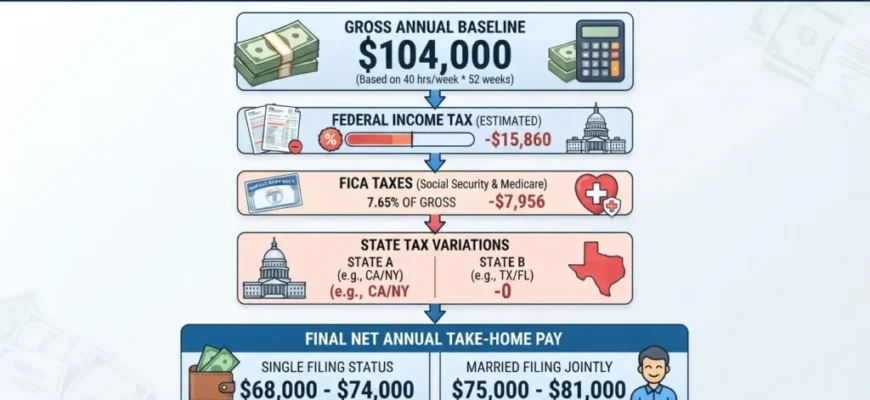
Before taxes, an hourly rate of $50 amounts to $104,000 a year. This calculation assumes a full-time work schedule of 40 hours per week and 52 working weeks in a year. Here’s the formula:
- Hourly Rate x Hours Per Week x Weeks Per Year = Annual Salary
- $50 x 40 x 52 = $104,000
Understanding Tax Deductions
Taxes can significantly reduce your take-home pay. Federal, state, and local taxes vary, making it necessary to have a good estimate of your tax obligations. Understanding tax brackets is essential for accurately calculating your net earnings.
In the U.S., federal tax brackets range from 10% to 37%. State taxes vary widely; for instance, California has a maximum rate of 13.3%, while some states like Texas have no income tax. To estimate after-tax income, you can use a tax calculator or consult tax professionals.
Yearly Income After Federal Taxes
Let’s make a rough estimation using federal taxes:
- Estimated Federal Tax Rate: 22% (could vary based on filing status and deductions)
- Annual Salary: $104,000
- Estimated Federal Tax: $104,000 x 22% = $22,880
- Net Income After Federal Tax: $104,000 – $22,880 = $81,120
State and Local Taxes
State taxes can further decrease your salary:
To calculate state taxes, it’s recommended to check your state’s tax rate and apply it to your taxable income. Don’t forget about local city or county taxes which might apply. For instance, New York City applies a local income tax that can range from 3% to 3.876%.
Social Security and Medicare Deductions
The U.S. government mandates additional deductions:
- Social Security Tax: 6.2%
- Medicare Tax: 1.45%
On a $104,000 salary:
- Social Security: $104,000 x 6.2% = $6,448
- Medicare: $104,000 x 1.45% = $1,508
Total Social Security and Medicare Deductions: $7,956
Net Income Calculation
To find your net income after all taxes, simply subtract all calculated taxes from your gross income:
Gross Income: $104,000
Total Federal, State, Local, Social Security, and Medicare Taxes: sum of all taxes
Net Income = Gross Income – Total Taxes
Table: Estimated Net Income
| Category | Amount |
|---|---|
| Gross Annual Income | $104,000 |
| Federal Tax (22%) | $22,880 |
| State Tax (5%, varies) | $5,200 |
| Social Security | $6,448 |
| Medicare | $1,508 |
| Net Income | $68,964 |
Practical Budgeting Tips
Understanding your take-home pay is just the beginning. Effective budgeting is crucial. Allocate your net income wisely between essential expenses, savings, investments, and discretionary spending. Financial advisors recommend the 50/30/20 rule: 50% on needs, 30% on wants, and 20% on savings.
Common Mistakes and How to Avoid Them
Avoid these mistakes when calculating your income:
- Underestimating variable taxes such as bonuses or freelance income
- Failing to account for potential deductions, such as retirement contributions
- Ignoring state-specific tax policies
FAQ: Common Questions About Hourly to Annual Income Conversion
- How do I calculate my annual income from hourly wages? Use the formula: Hourly Rate x Hours Per Week x Weeks Per Year.
- What percentage is taken out of my paycheck for taxes? Tax rates vary by federal, state, and local governments and depend on your income bracket.
- Why are federal tax rates different? Federal taxes are progressive; tax rates increase as income increases.
- How can I lower my taxable income? Consider tax-deductible contributions such as retirement accounts.
- Do all states have income tax? No, states like Texas and Florida do not have state income tax.