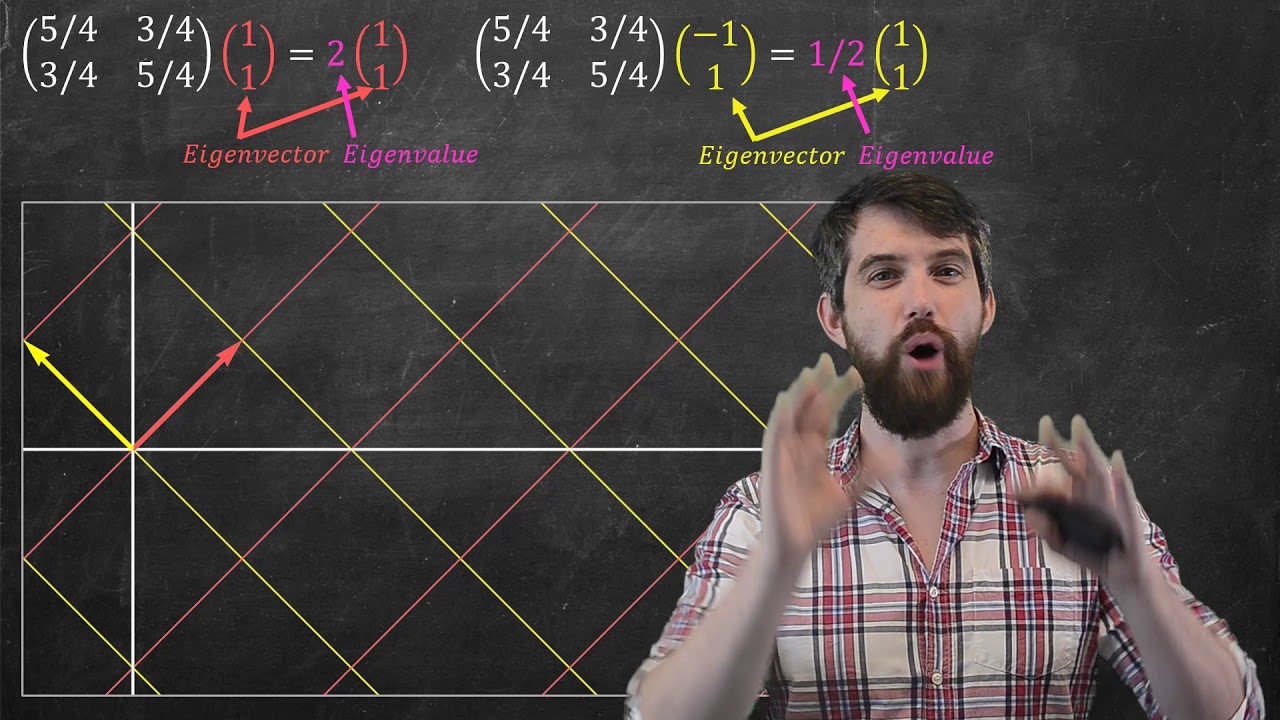
A matrix is diagonalizable if it has enough linearly independent eigenvectors (n for an n by n matrix), so it is similar to a diagonal matrix.
Definition
A square matrix A is diagonalizable if A = P D P^(-1), where D is diagonal and P is invertible.
Condition
An n x n matrix is diagonalizable if it has n linearly independent eigenvectors.
Easy case
If A has n distinct eigenvalues, it is diagonalizable.
Symmetric matrices
Real symmetric matrices are always diagonalizable.
Not diagonalizable

Matrices with defective eigenvalues, such as [[1,1],[0,1]].
Why useful
Makes powers of A easy to compute.
Definition and criterion
A square matrix A is diagonalizable if there is an invertible matrix P and a diagonal matrix D such that A = P D P inverse. The columns of P are eigenvectors of A, and the diagonal entries of D are the eigenvalues. A matrix of size n is diagonalizable exactly when it has n linearly independent eigenvectors.
- If a matrix has n distinct eigenvalues, it is diagonalizable.
- A matrix is diagonalizable if, for each eigenvalue, the geometric multiplicity equals the algebraic multiplicity.
- Real symmetric matrices are always diagonalizable by an orthogonal matrix, according to the spectral theorem.
Non-diagonalizable example and use
The matrix with rows (1, 1) and (0, 1) has a repeated eigenvalue 1 with only one independent eigenvector, so it is not diagonalizable. It has a Jordan block form. Diagonalization makes computing powers easy, since A to the k equals P D to the k P inverse, and it helps solve systems of differential equations, Markov chains and principal component analysis.
Definition and criterion
An n by n matrix is diagonalizable if it has n linearly independent eigenvectors, so that A = PDP inverse with D diagonal. Matrices with n distinct eigenvalues are always diagonalizable. Real symmetric matrices are diagonalizable.
Non diagonalizable example and use
The matrix with rows (1, 1) and (0, 1) has one eigenvalue 1 with a single eigenvector direction, so it is not diagonalizable. Diagonalization simplifies matrix powers.
Definition and test
A square matrix A is diagonalizable if there is an invertible matrix P and a diagonal matrix D such that A = P D P inverse. Equivalently, A has n linearly independent eigenvectors, where n is its size. The columns of P are the eigenvectors and the diagonal entries of D are the eigenvalues.

Conditions and examples
A matrix with n distinct eigenvalues is always diagonalizable. If an eigenvalue repeats, A is diagonalizable only if the geometric multiplicity (dimension of the eigenspace) equals the algebraic multiplicity for each eigenvalue. Real symmetric matrices are always diagonalizable, with orthogonal eigenvectors (the spectral theorem). The matrix with rows (1, 1) and (0, 1) is not diagonalizable because it has one eigenvalue 1 with only one independent eigenvector. Diagonalization makes powers easy, since A to the k equals P D to the k P inverse.
Based on data from MIT OpenCourseWare and Gilbert Strang’s Linear Algebra